Florida Panhandle · Escambia · Santa Rosa · Okaloosa
Roof repair, drywall, soffit and fascia, stucco, hurricane windows and pool cages. Permits, insurance claims, wind mitigation, the FEMA 50% rule, license checks and costs for Pensacola, Milton, Pace, Crestview, Fort Walton Beach, Destin and the surrounding Panhandle — from a Florida licensed general contractor.
Florida Licensed General Contractor · CGC1531095
Tell us what was damaged and where. We call back to schedule an inspection and send a written quote — no obligation.
We call back within one business day. Free, no-obligation quote.
What Happened
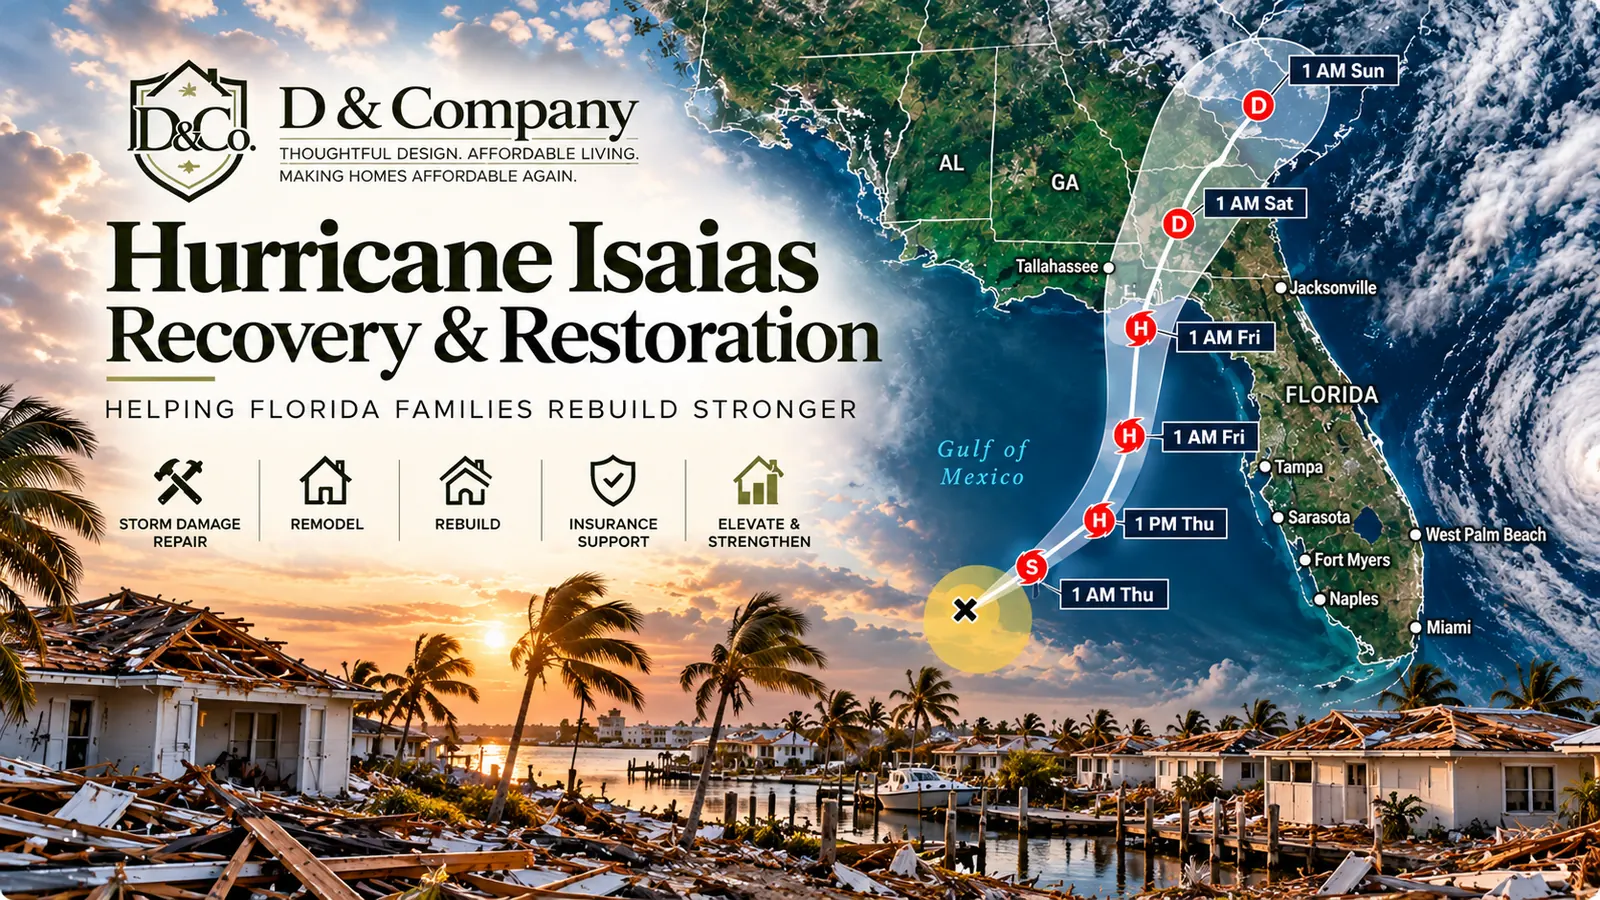
Hurricane Isaias made landfall near Destin on Friday, October 9, 2026, as a Category 2 storm with sustained winds of about 105 mph, according to National Hurricane Center information reported by CNN. The governor had declared a state of emergency covering 25 counties from Escambia County through the Big Bend.
Early reports described a roof ripped off a hotel in Pensacola, roofs peeled off at least two gas stations and a home in Gulf Breeze, the Milton High School gymnasium destroyed, flooded roads in Destin, and more than 420,000 Florida customers without power the day after landfall. Damage assessments are still being completed, so this page is a repair guide, not a damage report. Check the National Hurricane Center and your county emergency management office for official figures.
Homeowners move through three stages: emergency protection (tarps, board-up, water extraction), dry-out and demolition, and permitted reconstruction. Specialists such as tarping crews and mold remediators handle the first two stages. D&Co Homes handles the third: the code-compliant rebuild.
| Stage | When | What happens |
|---|---|---|
| 1. Emergency protection | First 72 hours | Photos, tarps and board-up, water extraction, insurance notice. Specialist crews. |
| 2. Dry-out & demolition | Days 3–21 | Remove wet drywall and insulation, dry framing, mold assessment. Licensed specialists. |
| 3. Permitted rebuild | Weeks 3 – months | Roof, drywall, soffit and fascia, stucco, impact windows and doors, pool cage. D&Co Homes. |
Insurance Claims & the 50% Rule
Claim steps: (1) photograph and video all damage before moving anything, (2) notify your insurer and get a claim number, (3) make reasonable temporary repairs and keep every receipt, (4) get a written estimate from a licensed contractor to compare with the adjuster’s, and (5) track your deadlines. Florida currently allows one year from the date of loss to give notice of an initial claim and 18 months for a supplemental claim, but your policy may require faster notice.
The 50% rule: if the cost to restore a building to its pre-damage condition equals or exceeds 50% of the building’s market value before the damage (land excluded), it is “substantially damaged” under 44 CFR 59.1. In a flood zone the home must then meet current floodplain standards, which can mean elevating it or rebuilding. Escambia County explains the rule on its flood repair permitting page. Florida’s 2025 SB 180 limits how many years of past improvements can be added together for the calculation. Ask your floodplain administrator for a written determination before committing to repairs.
This is general information, not legal or insurance advice. Confirm deadlines and coverage with your insurer or an attorney.
Permits
| County | What to know |
|---|---|
| Escambia County (Pensacola, Pensacola Beach) | Some post-hurricane work needs a permit and some does not; when one is required it must be issued before work starts. Emergency repairs to secure a structure are allowed. Apply online at mgoconnect.org or call Building Services at 850-595-3550. Offices: 3363 West Park Place, Pensacola, and 3470 N. Highway 29, Molino. On Pensacola Beach the Santa Rosa Island Authority floodplain administrator approves first. |
| Okaloosa County (Fort Walton Beach, Destin) | Re-roofing needs a permit. Before the final roof inspection, file a re-roof inspection affidavit with photos of the roof deck nailing pattern and the secondary water barrier. Roof-to-wall (hurricane clip) work is a separate permit with its own affidavit. |
| Santa Rosa County (Gulf Breeze, Milton, Navarre) | Permits come from Santa Rosa County or the city if your address is inside city limits. Confirm requirements with the building department before starting. |
Permits protect you. An unpermitted repair can complicate an insurance claim and cause problems when you sell. After a storm, counties sometimes waive permit fees or speed up reviews, so ask whether a waiver applies.
Check a License
After every hurricane, unlicensed storm chasers arrive. Before you sign anything, search the license at myfloridalicense.com or call the Department of Business and Professional Regulation at (850) 487-1395. Confirm that the license is active and covers the work.
During a state of emergency, unlicensed contracting is a third-degree felony in Florida, and out-of-state contractors still need a Florida license. Report suspected unlicensed work to DBPR at (866) 532-1440. D&Co Homes is a Florida Certified General Contractor, license CGC1531095, and you can verify it the same way.
Get a written contract with the scope, price, and payment schedule. Florida law generally limits the initial deposit to 10% of the contract price, and a contractor offering to cover or waive your insurance deductible is a red flag.
Services & Costs
These are typical Florida planning ranges, not quotes. Panhandle prices can run higher right after a storm because of demand. You receive a written quote after we inspect the damage. We do not offer emergency tarping, water extraction, or mold remediation; those are specialist jobs to complete first.
Wind lifts shingles, strips ridge caps, and drives water under underlayment. Even when the roof looks intact from the street, a lifted or creased shingle can leak at the next rain. We coordinate your roof through a licensed Florida roofing contractor partner who performs the roofing work and holds the roofing license; D&Co stays your single point of contact from estimate to final inspection. Metal roofing, including standing seam, is a common upgrade in the Panhandle for wind resistance and longevity; choose panels with a Florida Product Approval and a wind rating that fits your area.
| Job | Typical cost |
|---|---|
| Storm repair (partial: shingles, flashing, ridge) | $500 – $3,500 |
| Asphalt shingle roof replacement, typical home | $9,000 – $20,000 |
| Metal roof replacement (standing seam) | $22,000 – $55,000+ |
Wind-driven rain through a failed roof, window, or door soaks insulation and ceiling drywall within hours. Wet drywall that stays wet grows mold, so the sequence matters: dry out and remove what is destroyed, confirm the framing is dry, then rebuild. We handle the rebuild phase: hanging, taping, finishing, texture matching, baseboards, and paint.
| Job | Typical cost |
|---|---|
| Small patch or hole repair | $150 – $400 |
| Drywall hung, taped & finished | $1.50 – $3.50 / sq ft |
| Water-damaged section replacement | $300 – $1,200 |
| Texture matching / knockdown repair | $250 – $600 |
Soffit panels are one of the first things to blow out in a hurricane, and an open soffit lets wind-driven rain straight into the attic. Fascia boards hold your gutters and close the roof edge; once they are wet or torn loose, rot follows.
| Job | Typical cost |
|---|---|
| Spot fascia repair (localized rot) | $8 – $15 / linear ft |
| Full fascia replacement | $10 – $20 / linear ft |
| Fascia + soffit replacement | $18 – $25 / linear ft |
Wind-borne debris cracks and chips stucco, and cracks let water reach the wall framing behind it. Stucco repair after a storm needs the damaged area opened up, the lath and weather barrier checked, and the new coats matched and cured properly.
| Job | Typical cost |
|---|---|
| Small crack or patch repair | $300 – $800 |
| Full stucco installation (3-coat) | $6 – $9 / sq ft |
| EIFS (synthetic stucco) repair | $400 – $1,200 |
| Whole-house re-stucco | $7,000 – $15,000 |
Broken windows and blown-out sliding doors turn a storm into a total loss of the interior. Replacing them with impact-rated products protects against the next storm and, in the Wind-Borne Debris Region, is how openings are normally code-compliant.
| Job | Typical cost |
|---|---|
| Impact window, installed (typical) | $500 – $1,500 / window |
| Whole-home impact window package (3 bed / 2 bath) | $12,000 – $25,000 |
| Permits & inspection | Varies by city / county |
Pool cages are designed to let wind pass through the screen, and when they fail it is usually because the screens were left in place or the frame was already corroded. Small damage can be rescreened; bent frames, leaning columns, and failed fasteners mean replacement.
| Job | Typical cost |
|---|---|
| Rescreening (frame is sound) | $8 – $18 / sq ft area |
| Typical full pool enclosure replacement | $8,000 – $30,000+ |
| Engineering, permit & inspection | $300 – $2,000 |
Your City
Each city sits under a different permitting office, and storm impacts varied along the coast. Here is what to know locally.
Pensacola was one of the hardest-hit areas in early reports: a hotel roof was ripped off, police asked residents to stay off streets blocked by debris, and Escambia County had widespread outages and downed trees. Repairs here fall under Escambia County Building Services or the City of Pensacola depending on whether your address is inside city limits, so confirm which applies before applying. Escambia accepts permit applications online at mgoconnect.org, and its offices are the Central Office Complex at 3363 West Park Place in Pensacola and the Molino office at 3470 N. Highway 29. On Pensacola Beach, the Santa Rosa Island Authority floodplain administrator must approve the request before it goes to Building Services.
Reports after landfall described gusts peeling roofs off at least two gas stations and a home in Gulf Breeze. The peninsula sits in Santa Rosa County, and some addresses are inside Gulf Breeze city limits while others are unincorporated, which changes who issues your permit. Waterfront and low-lying parcels may also be subject to floodplain rules, so the substantial damage question comes up early for homes close to the bay or sound.
Milton is the Santa Rosa County seat, and the Milton High School gymnasium was reported destroyed in the storm, a sign of the wind strength inland from the coast. Inland homes face a different risk than beachfront ones: falling trees, roof and soffit damage, and wet interiors rather than surge. Santa Rosa County has its own permit process, separate from Escambia, so use the county building department for your address.
Pace is an unincorporated community in Santa Rosa County, between Pensacola and Milton, and it is one of the larger roofing-search markets in the Panhandle. Permits for unincorporated addresses come from Santa Rosa County, not a city. Inland homes like those in Pace are most likely to need roof, soffit, and fascia repair, tree-damage repair, and interior drywall rebuild after wind-driven rain, rather than surge-related flood repair.
Crestview is the Okaloosa County seat, inland and north of Fort Walton Beach. Okaloosa County permit rules apply to roofing, including the re-roof inspection affidavit and the photos of the roof deck nailing and secondary water barrier. Homes inland often see wind, falling-tree, and roof damage rather than coastal flooding. The City of Crestview may handle its own permitting inside city limits, so confirm which office covers your address.
Fort Walton Beach is in Okaloosa County, right next to the landfall area. Okaloosa requires a permit to replace roofing and, before the final roofing inspection, a re-roof inspection affidavit with photos of the roof deck nailing and secondary water barrier. Roof-to-wall connection work (hurricane clips) is a separate permit with its own affidavit. The City of Fort Walton Beach may handle its own permitting inside city limits, so verify which office applies.
Niceville is in Okaloosa County on Boggy Bayou and Choctawhatchee Bay, north of Destin. Roofing permits follow Okaloosa County rules, and bayfront parcels may fall in a flood zone, which brings the substantial damage (50% rule) question into play. Confirm whether your address is inside Niceville city limits or unincorporated Okaloosa County before you apply for a permit.
The storm made landfall near Destin, and roads in Destin flooded during it. Okaloosa County permit rules apply to roofing, and beachfront properties may also fall under the state’s Coastal Construction Control Line rules, which add review to work seaward of the line. After flood damage, the substantial damage question (the 50% rule) comes up quickly for older coastal homes, and the answer decides whether you repair or rebuild to current flood elevation standards.
Santa Rosa Beach and the 30A communities are in Walton County, east of Destin, so permits come from Walton County rather than Okaloosa. I did not find detailed Isaias damage reports for this area, so confirm conditions locally. Beachfront properties along 30A may be subject to the state’s Coastal Construction Control Line and flood-zone rules, which affect how storm repairs are permitted and whether the 50% rule applies.
FAQ
Jump to: After the Storm · Insurance Questions · Hiring a Contractor After a Storm · Roofing · Metal Roofing · Wind Mitigation Inspections · Drywall & Interior Rebuild · Soffit & Fascia · Stucco · Impact (Hurricane) Windows & Doors · Pool Cages & Screen Enclosures · Local Questions
After the Storm: Claims, Permits & the 50% Rule
Make the home safe, then stop further damage. Take photos and video of everything before you move or throw anything away, tarp the roof or board openings if you can do it safely (or hire a specialist for emergency tarping), and call your insurer. Keep receipts for emergency repairs. Escambia County allows emergency repairs to secure a structure without waiting on a permit, but permanent repairs generally need one.
Report the loss to your insurer as soon as possible, document damage with dated photos and video, and keep a written list of damaged items. Make reasonable temporary repairs and save receipts. Ask for the claim number and the adjuster’s contact details. Get a written repair estimate from a licensed contractor to compare with the insurer’s estimate. This is general information, not legal or insurance advice.
Florida law currently sets a deadline of one year from the date of loss to give notice of an initial or reopened claim and 18 months for a supplemental claim (changed in 2022 by SB 2-A). Your policy may require faster notice, so report the loss right away and confirm the deadlines with your insurer or an attorney.
If the cost of restoring a building to its pre-damage condition equals or exceeds 50% of the building’s market value before the damage (land excluded), it is “substantially damaged” under federal rules (44 CFR 59.1). In a floodplain, the building must then be brought into compliance with current floodplain standards, which can mean elevating it, using flood-resistant materials, or rebuilding. The rule applies in communities that participate in the National Flood Insurance Program.
Your local floodplain administrator, using the cost to fully repair the structure and its market value, which is typically based on the county property appraiser’s building value or a licensed appraisal. Splitting repairs into phases does not avoid the rule, because the determination is based on the cost to fully restore the building. Contact your county floodplain office before starting repairs.
Often yes. Escambia County says post-hurricane work may or may not require a permit; when one is required, it must be issued before construction starts. Emergency repairs to secure a structure are treated differently. Re-roofing requires a permit. Contractors can apply online at mgoconnect.org; call Building Services at 850-595-3550 to confirm what your repair needs.
Replacing roofing materials requires a permit in Okaloosa County, and before the final roof inspection you must file a re-roof inspection affidavit with photos of the roof deck nailing and the secondary water barrier. Roof-to-wall connection work is a separate permit with its own affidavit. Confirm other repairs with Okaloosa County Growth Management.
Generally yes, as an emergency measure to secure the structure from further damage, and Escambia County explicitly allows emergency repairs for safety and security. Keep photos of the damage first, and keep every receipt. Permanent roof repair or replacement is a separate step that needs a permit.
Insurance Questions
Standard Florida homeowners policies generally cover wind damage from a hurricane, including roof and window damage, but not flood. Hurricane losses usually carry a separate hurricane deductible, often a percentage (commonly 2% to 5%) of your dwelling coverage, so read your policy declarations page. Confirm coverage and deductible with your insurer.
No. Standard homeowners policies exclude flood damage. Flood is covered by a separate National Flood Insurance Program policy or a private flood policy. If storm surge or rising water entered your home, report it under your flood policy and ask whether the 50% rule applies.
Dated photos and video of the damage, a written repair estimate from a licensed roofing contractor, your policy number and claim number, and receipts for emergency repairs. Keep damaged materials until the adjuster has seen them, if you can do so safely. Ask the roofer to document the roof deck and underlayment condition during the work.
Re-roofing requires a permit, and an unpermitted roof can complicate a future claim and a sale. In Okaloosa County the re-roof inspection affidavit and photos of the roof deck and secondary water barrier become part of the record. Use a contractor who pulls the permit.
Hiring a Contractor After a Storm
Search the license number at myfloridalicense.com or call the Department of Business and Professional Regulation at (850) 487-1395 before you sign. Confirm the license is active and covers the work. D&Co Homes holds Florida Certified General Contractor license CGC1531095, which you can verify the same way. County-licensed trades can be checked with the county contractor licensing office.
In Florida, unlicensed contracting activity is normally a misdemeanor, but during a state of emergency declared by the Governor it becomes a third-degree felony. Report suspected unlicensed work to the DBPR Unlicensed Activity hotline at (866) 532-1440.
Only if they hold a Florida license. DBPR warns that out-of-state contractors often travel to disaster areas, and a license from another state does not allow them to work on a Florida home or business. Ask for a Florida license number and verify it before signing anything.
Florida law generally limits the initial deposit on a construction contract to 10% of the contract price, with exceptions such as custom-ordered materials. Be wary of anyone demanding a large cash payment up front after a storm. Get a written contract with scope, price, and payment schedule, and check the law with your attorney if the contract asks for more.
Florida law generally prohibits contractors from paying, waiving, or rebating an insurance deductible, and it can be treated as insurance fraud. Treat any contractor who offers to “cover your deductible” as a red flag.
Roofing
D&Co is a Florida Certified General Contractor (CGC1531095). Under Florida law, roofing is performed by a licensed roofing contractor, so we coordinate your roof through a licensed, insured Florida roofing contractor partner who performs the roofing work and holds the roofing license. D&Co stays your single point of contact from estimate through final inspection.
Not necessarily. Florida’s 25% rule was changed in 2022 (SB 4-D, Fla. Stat. 553.844): if the roof was built, repaired, or replaced under the 2007 Florida Building Code or later, only the repaired portion generally has to meet current code, even if 25% or more is replaced. Older or unpermitted roofs are treated differently. Your building department and the inspection of the roof decide.
Temporary repairs such as tarping vary widely by roof size and access, and are usually a specialist job done in the first days after a storm. A permanent storm repair of shingles, flashing, and ridge caps typically runs $500–$3,500, while a full shingle replacement for a typical home runs about $9,000–$20,000. We give a written quote after inspecting the roof.
Verify the Florida roofing license at myfloridalicense.com, confirm active liability and workers’ compensation insurance, ask who pulls the permit, and get a written estimate with scope, materials, and payment schedule. Be wary of door-to-door storm chasers and large upfront payments. D&Co coordinates your roof through a licensed Florida roofing contractor partner.
The roof area and scope, materials and brands, underlayment and deck repair allowances, permit cost, removal and disposal, warranty terms, the roofer’s license number, start and finish dates, and payment schedule. Estimates that only give a lump sum with no scope are hard to compare.
Florida requires a state roofing license issued by DBPR, either Certified (CCC) or Registered, to perform roof repairs and replacements. Check the license number at myfloridalicense.com. D&Co Homes holds Certified General Contractor license CGC1531095 and coordinates roofing through a licensed roofing partner who holds the roofing license.
Planning ranges are about $9,000–$20,000 for an asphalt shingle roof on a typical home and $22,000–$55,000+ for standing seam metal, depending on roof size, pitch, deck condition, and material. Prices can rise right after a storm because of demand, so get a written quote that separates materials, deck repair, permit, and disposal.
Metal Roofing
Typically $22,000–$55,000 or more for an average home, depending on roof size, panel gauge, and complexity. Metal costs more upfront than shingles but is a common choice in wind-prone areas. Choose panels with a Florida Product Approval and a wind rating that fits your area, and confirm the install details with your building department.
Properly installed metal roofs with the right fasteners, underlayment, and edge details can perform well in high winds, but performance depends on the installation and the product approval, not the material alone. Ask for the panel’s tested wind rating and the fastening schedule used.
Wind Mitigation Inspections
A wind mitigation inspection documents the features of your home that reduce hurricane damage, such as roof covering, roof deck attachment, roof-to-wall connections, secondary water barrier, and opening protection. The inspector completes Florida’s uniform mitigation verification form, which your insurer uses to calculate wind premium discounts.
Inspections are commonly quoted in the range of about $75 to $150 per home, depending on the inspector and home size. Prices vary, so ask what the report includes and how fast you will receive it.
Yes. A new roof with an upgraded deck attachment, secondary water barrier, or roof-to-wall connections can qualify for larger insurance discounts. Ask your roofer to document the deck nailing and secondary water barrier during the work, and then schedule the inspection. Insurers generally accept a mitigation form for five years, but confirm with your insurer.
Florida allows qualified licensed professionals, such as licensed contractors, engineers, architects, building code inspectors, and certified home inspectors, to complete the uniform mitigation verification form. D&Co coordinates the repair; ask your insurer which inspector credentials it accepts.
Discounts are tied to the features verified on the inspection form. After repairs, request a new inspection so the updated roof and openings are reflected in your premium. The amount of the discount depends on your insurer and the features verified.
Drywall & Interior Rebuild
Drywall and insulation that stayed wet or were soaked by contaminated water are typically removed, usually cut above the visible waterline, and the framing is dried before rebuilding. Roof leaks that dampen only part of a ceiling may be dried or patched. Because mold can grow within days, have the damage assessed early.
Typical Florida ranges: $150–$400 for a small patch, $1.50–$3.50 per square foot to hang, tape, and finish, and $300–$1,200 to replace a water-damaged section. Whole-room rebuilds depend on insulation, paint, and trim. We give a written quote after seeing the damage.
Match the existing texture, commonly orange peel, knockdown, or smooth, using the same spray or hand technique so the repair blends. Texture matching typically runs $250–$600. Popcorn ceiling removal is a separate job, usually $400–$900 per room.
Small cracks can be taped and finished, but a ceiling that sagged, bubbled, or stayed wet is usually replaced because the paper and gypsum lose strength. Find and fix the roof leak first, then replace and refinish the ceiling.
Porous materials like drywall with visible mold are generally removed rather than cleaned. For larger areas, the EPA recommends hiring a professional. Florida licenses mold assessors and remediators separately, so use a licensed specialist for remediation, then D&Co handles the drywall rebuild.
In bathrooms, laundry rooms, and other damp areas, moisture-resistant (green or purple board) drywall is a good choice. It is not a substitute for drying out the wall: it resists humidity but is not flood-proof.
Soffit & Fascia
Wind pressure gets behind soffit panels and pushes them out, which lets wind-driven rain into the attic and wets insulation and ceilings. Replacing soffit and fascia promptly protects the attic and the roof edge, and it should be done with the roof work so the edge is sealed.
Typically $8–$25 per linear foot depending on material and rot: about $8–$15 for spot fascia repair, $10–$20 for full fascia replacement, and $18–$25 for fascia plus soffit replacement.
Stucco
Small hairline cracks can be sealed and patched, but cracks that open into the wall, hollow-sounding stucco, and staining mean water may have reached the lath, sheathing, or framing. Those areas are opened, repaired, and re-coated in layers so the patch does not crack again.
Small cracks and patches typically run $300–$800, EIFS (synthetic stucco) repair $400–$1,200, full three-coat stucco about $6–$9 per square foot, and whole-house re-stucco $7,000–$15,000.
Impact (Hurricane) Windows & Doors
In the Wind-Borne Debris Region, window and door openings must be protected by impact-rated glazing or approved shutters, and products must have a Florida Product Approval. Most coastal Panhandle areas are in this region, but the building department confirms it for your parcel. The stricter Miami-Dade HVHZ product approvals do not apply in the Panhandle.
Typical installed prices run about $500–$1,500 per window, and a whole-home package for a three-bedroom, two-bath home commonly runs $12,000–$25,000 depending on size, frame, and glass. Custom-ordered products can have lead times of several weeks, so order early after a storm.
Pool Cages & Screen Enclosures
If the aluminum frame is straight and the fasteners are sound, rescreening is the economical option. If columns are bent, the frame is leaning, or fasteners are corroded or pulled, the cage should be replaced. A contractor or engineer should inspect it before you rescreen.
Replacement enclosures are generally engineered to Florida Building Code wind loads and permitted, with engineering, plan review, and inspections costing roughly $300–$2,000 depending on the city or county. Rescreening an undamaged frame often does not require a permit; confirm with your building department.
Local Questions: Pensacola, Gulf Breeze, Milton, Pace, Navarre, Crestview, Fort Walton Beach, Niceville, Destin & Santa Rosa Beach
Escambia County Building Services issues permits for unincorporated Escambia addresses, and the City of Pensacola may handle addresses inside city limits. Escambia accepts online applications at mgoconnect.org and permits@myescambia.com for applications without plans. Confirm which office covers your address before you apply.
On Pensacola Beach, the Santa Rosa Island Authority floodplain administrator must approve a permit request before it goes to Escambia Building Services. Beachfront homes also face the substantial damage (50% rule) question and Coastal Construction Control Line review, so start with the floodplain office.
It depends on the address. Some Gulf Breeze addresses are inside city limits and others are unincorporated Santa Rosa County, and permits come from different offices. Check your property record or call the county before applying.
It applies to buildings in the floodplain in communities that participate in the National Flood Insurance Program. Homes near the bay or sound are the most likely to be in a flood zone, and the local floodplain administrator determines whether repair costs reach 50% of the building’s value.
Milton is in Santa Rosa County, so permits come through Santa Rosa County (or the City of Milton if the address is inside city limits). Roof replacement, structural repair, and window or door replacement generally require permits; confirm requirements for your repair with the building department.
Wind and tree damage were the main reported inland risks, but low-lying and creek-adjacent parcels can also flood. Check your flood zone through the county, and confirm whether any repair is subject to floodplain rules before you start.
Most of Navarre is unincorporated Santa Rosa County, so the county building department issues permits. Navarre Beach is a leasehold community managed by the county that can carry additional requirements, so confirm if your address is on the beach.
Possibly. Leasehold barrier-island properties can have lease and county review requirements in addition to building permits. Call the county before planning the work.
A building permit, and before the final roofing inspection a re-roof inspection affidavit with photos of the roof deck nailing pattern and the secondary water barrier, labeled with your permit number or address. Roof-to-wall (hurricane clip) work is permitted separately. The City of Fort Walton Beach may issue permits inside city limits.
Addresses inside Fort Walton Beach city limits may be permitted by the city, while unincorporated addresses use Okaloosa County. Check your property record or call Okaloosa Growth Management to confirm before applying.
The storm made landfall near Destin, and flooding hit local roads. Okaloosa County permit rules apply to roofing, beachfront parcels may be subject to the state’s Coastal Construction Control Line, and the substantial damage (50% rule) determination should be made before you commit to repairs on flood-damaged homes.
Yes. D&Co is a Florida Certified General Contractor (CGC1531095), and Florida GC licensure is statewide. We coordinate roofing through a licensed roofing contractor partner and take on drywall and interior rebuild, soffit and fascia, stucco, impact windows and doors, and pool cage work. Submit the form for a written quote.
Pace is unincorporated Santa Rosa County, so permits come from the county building department rather than a city. Confirm requirements for roofing, soffit and fascia, and interior rebuild before starting.
Crestview is in Okaloosa County, and the City of Crestview may issue permits inside city limits while unincorporated addresses use the county. Roofing requires a permit, with the re-roof affidavit and deck and secondary water barrier photos before final inspection.
Addresses inside Niceville city limits may be permitted by the city, while unincorporated addresses use Okaloosa County. Check your property record or call Okaloosa Growth Management to confirm before applying.
Santa Rosa Beach and the 30A communities are in Walton County, so permits come from Walton County rather than Okaloosa. Beachfront parcels may also be subject to the Coastal Construction Control Line and flood-zone rules.